18+. The welcome offer shown here is the one the partner gives the site owner; availability depends on your country and your eligibility. Bonus size, qualifying deposit, wagering, eligible games, maximum bet, expiry and withdrawal limits are set out in the operator’s own terms and are not repeated here. We do not promise payout times. Offshore operator, not licensed by the Gambling Commission of Great Britain. Gambling involves financial risk — free confidential help at begambleaware.org, 0808 8020 133.
Short answerThis is the step where the payment stops being the difficult part and the conditions attached to it take over. It is also the first step at which taking money out is a realistic prospect, which brings a second floor into view.
Our top pick
22BET — 100% up to £100 on your first deposit
Regulator
Gambling Commission of Great Britain
Credit cards
Banned for gambling since April 2019
Minimum age
18
Tax on winnings
None for the player
Self-exclusion
GAMSTOP, free and nationwide
The step where an offer arrives whole rather than in part
Ten pounds is the step at which the cashier stops being the interesting part. The route will carry it, the desk will accept it, and a qualifying clause is generally satisfied without having to be worked at. What remains is the offer itself, arriving in one piece instead of the half-triggered state that smaller payments tend to produce. The questions change to match: not whether the payment will work, but what it has signed you up to.
It is also the first step where the other direction becomes a genuine subject. A balance built from this figure can plausibly reach the point of being requested, which is not a sentence that can honestly be written about the smallest steps. So the page runs in two halves. The first is what the first deposit offer does once it is whole. The second is what the way out costs in time, routes and documents.
Two floors facing each other across one account
An account has a floor at each end. One is the least the desk will take into a balance; the other is the least it will send out of one. They are written by the same operator, on different pages, for different reasons, and nothing obliges them to agree. The first covers the cost of carrying a customer. The second covers the cost of making a payment and reviewing it beforehand, which is a different sort of cost altogether.
Where the second sits higher than the first, a gap opens that is easy to walk straight into: an account funded perfectly legitimately, holding a balance too small to be requested. Reading the floors and caps on payouts at the same sitting as the deposit screen closes that gap before it opens. It is a two-minute job in the right order and a thoroughly annoying one in the wrong order.
What you are comparing
The floor on the way in
The floor on the way out
What it covers
The cost of carrying an account
The cost of paying out and reviewing first
Where it is published
Beside the amount field in the cashier
The withdrawal part of the site terms
When you meet it
Before the first payment is made
After a balance already exists
How it varies
By method, at the operator's choice
By method and sometimes by account
The two floors on one account
Why the floor on the way out sits where it does
A payout is not the mirror image of a deposit. A deposit is a push you authorise; a payout is a decision somebody makes, and decisions have a person-sized cost attached to them. Something has to confirm that the balance is genuinely withdrawable, that the account has been verified, that no condition is outstanding and that the destination belongs to the account holder. None of that work gets smaller when the amount does.
So the floor exists for the same reason the deposit floor does, only pointing the other way: below some figure the review costs more than the payment is worth. Desks that pay small balances out anyway tend to do it on a restricted set of routes, or to fold the cost into a charge, or to require that the whole balance leaves in one go. Those are three answers to one problem, and all three are published rather than hidden.
None of this is the same question as whether a desk pays at all. A floor is a published rule applying to everyone; a refusal to pay a balance that already meets the floor is a dispute, and the two get confused constantly. Checking the figure before asking tells you which of the two you are in, and that distinction decides whom you complain to and about what exactly.
A balance below the payout floor is early, not stuck
The situation is less serious than it feels. A balance that cannot yet be requested has not been taken from you; it is short of the figure the desk pays at. Three honest routes forward exist: carry on and reach the figure, ask whether the desk will close the whole balance out in a single payment, or leave it where it is. Which of the three is available is in the terms, and support can confirm it in one written sentence.
What makes the whole situation avoidable is doing the arithmetic in advance, in the order described under the stack of deposit floors: the route's figure, the desk's figure, the qualifying amount if you want one, and then the payout figure. That last one decides whether what you are building is a balance or a payout in waiting, and it is the one almost nobody looks at before paying anything in.
Money goes back the way it came
Payouts return along the path the money arrived on as far as that path allows. This is neither courtesy nor preference: sending funds back to their source is how a desk demonstrates it has not been used to shift money between unrelated accounts. The consequence is worth stating plainly, because it is counter-intuitive — the route chosen at the door sets the route at the exit, weeks before anybody thinks about leaving.
Where the original route cannot receive money, the desk substitutes one that can, and substitution is where the delay lives. A replacement has to be in your name and it has to be evidenced. That is why a transfer to a bank ends up carrying so many payouts even when nobody deposited that way: it is the route that can always receive, provided the account has been shown to be yours.
The same principle explains a rule that looks petty from the outside: a desk will refuse to pay a third party, however reasonable the explanation sounds. The destination has to carry your name, because the name is the entire point of the exercise. A joint account, a partner's card and a wallet registered to somebody else all fail that test, and correspondence does not change it.
The route in and the route out are rarely identical
Deposit lists and payout lists overlap without matching, and the mismatch is structural rather than arbitrary. Some routes can only push: a phone bill, a cash voucher. Some can work in both directions but only back to the same instrument, as a card does. Some were built for both from the beginning. A route resting on bank authentication, such as a payment through open banking, identifies the account at the moment of payment, which is why it creates so little friction afterwards.
The working rule is to choose the deposit route with the exit already in mind. If the easiest way in cannot pay out, add a route that can and have it verified while nothing is pending. Done on a quiet day that is paperwork; done on the day you want money it is a wait, and the wait gets blamed on the desk when it was created by the choice of route.
At the exit the identity check stops being optional
Checks can fire at any point, but there is one moment at which they cannot be deferred: the first request to take money out. A licensed desk has to know who holds the account and that the destination belongs to that person before it sends anything, and no amount of politeness compresses the step. That is why a first payout is so often slower than every payout after it. What is being processed is the account, not the payment.
The useful consequence is that this work can be moved in time but not avoided. Proving who you are before there is a balance worth arguing about turns the first payout into an ordinary one. One British particular is worth knowing here: a player's winnings carry no tax, so none of the questions put to you are tax questions. They are about identity, address and ownership of the method, and nothing else.
One detail catches people out. A person can be cleared while a payment method still is not. Clearing an account settles who you are and where you live; clearing a method settles that the card or account you want paid belongs to you. Add a new destination later and the second check runs again, even though the first was finished months earlier.
One payment of ten is not two payments of five
Arithmetically they are the same money. Contractually they are not. A clause asking for a single qualifying payment is satisfied by one of them and not by the other, which is the main reason the step below this one produces so many complaints about offers that never appeared. The desk is not adding up a total; it is testing individual payments against a condition, and a total is not a payment.
Splitting also changes what an offer costs to clear. Where turnover is calculated on bonus plus deposit, the size of the qualifying payment feeds straight into the obligation, so a larger single deposit makes the arithmetic bigger as well as the balance. Working through turnover attached to a bonus before choosing between one payment and two is the difference between picking a figure and being handed one.
The charge question, and who is allowed to answer it
Two parties can take something out of a payout, and they are not the same party. The desk may apply a charge on certain routes or in certain circumstances, and where it does, that charge is in its own terms. Your provider may apply something as well — a currency conversion, a handling charge on an inbound payment — and that lives in your provider's terms, where the desk has neither visibility nor any say.
So the right question is never whether withdrawals are free but who charges what on this particular route, and both answers are published. The desk's belong on the same page as its payout floor; your provider's belong in the documentation you accepted when the account was opened. A different question, regularly confused with this one, is what a game returns over time, which is a property of the game rather than anything the cashier decides.
Who
What they may apply
Where it is written
The operator
A charge on some routes or circumstances
The withdrawal part of the site terms
Your bank, wallet or network
Conversion, or a charge on an inbound payment
That provider's own terms and schedule
Nobody, on the tax side
A player's winnings are untaxed in the United Kingdom
A rule of the market, not a desk policy
Who can take something out of a payout
What ten pounds does not buy: a quicker payout
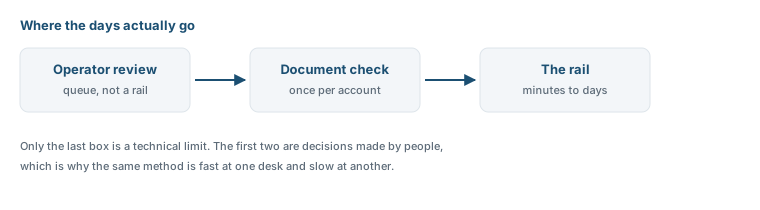
The size of a deposit has no effect on how fast money comes back. The wait has three segments and only one of them is technical. First the desk decides to release the payment, which is a queue staffed by people. Then, if the account has not been cleared, documents are checked, and that happens once per account rather than once per payment. Only after both does the rail move the money, and the rail is the quickest of the three.
This is why an identical method is brisk at one desk and sluggish at another, and why payouts described as fast are usually describing the queue rather than the rail. It is also why how long a payout takes cannot be answered by naming a method on its own. The one segment you control is the middle one: clear the documents and it disappears permanently.
Only the last box is a technical limit. The first two are decisions made by people.
Read the withdrawal page before the deposit page
The habit worth forming runs backwards from the obvious one. Open the withdrawal section first and note four things: the floor, the routes listed, whether the whole balance has to leave at once, and what the desk says about charges. Then open the cashier and pick a deposit route that also appears on the payout list. The exercise takes less time than reading one set of offer terms and removes most of the surprises that arrive later.
While you are reading, confirm whom you are reading. The register of licensed operators names the company behind the desk and is searchable at gamblingcommission.gov.uk. The same part of the site that explains how a payout is requested normally sets out the complaints route as well, and knowing both before you need either is the cheapest preparation on offer.
Keeping money back instead of paying more in
There is a decision at this step that attracts very little attention: not depositing again. Once a balance exists and the conditions on it are known, the alternative to another payment is to stop and let the balance stand. That is not caution for its own sake. It is the only way to learn what the exit actually looks like, because an account that never requests a payout never finds out how long its first one takes.
Testing the exit with one modest request is more informative than any article about it, this one included. You find out whether the documents are in order, how long the queue runs, which route the desk really uses and whether anything is deducted on the way. All of that is knowledge about one specific desk, which happens to be the only desk whose behaviour affects you.
That information is worth more early than late. A desk whose first payout goes through cleanly is one you can keep using with larger balances; a desk that asks for a document you cannot produce is better discovered while the sum at stake is small. Either way the test costs one request, and the answer holds for every payout after it.
The order that saves the most time
Read the exit, then the entrance. Choose a route that works in both directions, or add a second one that does and get it verified while nothing depends on it. Settle the offer question before the payment rather than after, since the clause attaches at the moment the money counts. Then make one payment instead of several, because a single payment satisfies clauses that a sequence of smaller ones does not.
In that order the step costs a few minutes of reading and produces no surprises at all. In the usual order it produces a balance that cannot leave, a document request on an inconvenient day and an argument about a charge nobody mentioned. And if the figure that is hard to settle is how much rather than how, free and confidential help is at begambleaware.org, and the National Gambling Helpline is on 0808 8020 133.
Questions people ask
Why treat ten pounds as a separate step at all?
Because it is the point at which the cashier stops being the constraint and the conditions take over, and the first point at which taking money out is realistic. Below it, the questions are about whether a payment will clear. Here they are about what the payment obliges you to do and how the balance eventually leaves.
Can the minimum payout be higher than the minimum deposit?
It can, and frequently nothing prevents it. The two figures are set separately, cover different costs and are published in different places. Check the withdrawal section before deciding how much to pay in.
What happens to a balance below the payout floor?
It stays on the account. The options are to reach the figure, to ask whether the desk will close the entire balance out in one payment, or to leave it alone. The terms say which of those exist, and support can confirm the answer in writing.
Does a payout have to go back to the deposit method?
Wherever that method can receive money, as a rule yes, because returning funds to source is how a desk shows it is not moving money between unrelated accounts. Where the route cannot receive, the desk substitutes one that can. You will then be asked to prove the substitute belongs to you.
Does a bigger deposit make the payout faster?
No. The wait is mostly a queue, plus a document check on a first payout, and the rail itself is the quickest part of it. The size of what you paid in changes none of those three segments.
Will anything be deducted from a payout?
Possibly, by either of two parties. The operator may charge on certain routes, which is in its terms, and your own provider may apply conversion or an inbound charge, which is in theirs. Ask about the specific route rather than about withdrawals in general.
Are winnings taxed?
Not for the player in the United Kingdom. That is why none of the questions in a payout check are tax questions: they concern identity, address and ownership of the payment method. Nothing in the process is a tax procedure.
Why is the first payout so much slower than the rest?
Because the account is being established at the same time as the payment is being made. Once documents are cleared they stay cleared, so the step happens once. Doing it before a balance exists takes it out of the first payout altogether.
Deposit again, or test the exit first?
One modest request tells you more about a desk than any amount of reading. You learn whether the documents are in order, how long the queue runs, which route is actually used and whether anything is deducted. That is information about the desk you are using rather than about desks in general.
Does an offer have to be taken at this step?
No. A plain deposit keeps the balance free of turnover conditions and stake ceilings, which matters if you expect to request money soon. Taking an offer is a trade, and the terms set out both halves of it.
 UK Cash DeskOpen the cashier


 100% up to £100 on your first deposit