18+. The welcome offer shown here is the one the partner gives the site owner; availability depends on your country and your eligibility. Bonus size, qualifying deposit, wagering, eligible games, maximum bet, expiry and withdrawal limits are set out in the operator’s own terms and are not repeated here. We do not promise payout times. Offshore operator, not licensed by the Gambling Commission of Great Britain. Gambling involves financial risk — free confidential help at begambleaware.org, 0808 8020 133.
Short answerA wallet deposit is still a pull, but the request stops at the wallet instead of reaching your bank. The site learns a wallet address and nothing behind it, PayPal applies its own gambling policy before your bank is ever asked, and a payout comes back into the wallet rather than straight onto the card you funded it with.
Our top pick
22BET — 100% up to £100 on your first deposit
Regulator
Gambling Commission of Great Britain
Credit cards
Banned for gambling since April 2019
Minimum age
18
Tax on winnings
None for the player
Self-exclusion
GAMSTOP, free and nationwide
What a wallet is doing in a cashier
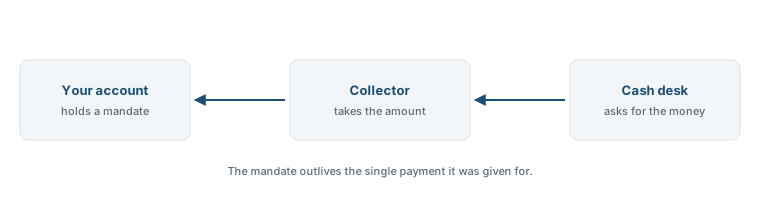
Strip the branding away and a wallet is an account that pays on your behalf. You hold a balance in it, or you hold permissions in it that let it reach a card or a bank account of yours. When a cash desk asks the wallet for money, the wallet answers from whichever of those it has, and the desk never has to know which one it used.
That single piece of indirection is the whole product. It is why the same button can be funded three different ways on three different days, why a site you have used once cannot keep hold of your card details, and why a failure here is harder to diagnose than a failure on a bare card. The chain has one more link in it, and the extra link has opinions.
Everything else on this page follows from the indirection. If you want the general shape first, the families of rail are laid out on the hub for payment routes, and the wallet family is the one defined by having a middleman that can refuse on its own authority.
Who sees what in a wallet deposit
Four parties are involved and each one holds a different slice of the picture. You see a single confirmation. The cash desk sees an identifier for your wallet, the amount and whether the request succeeded. The wallet sees both ends: it knows who the merchant is, what category the merchant trades in, and which of your funding sources it reached for. Your bank or card issuer, at the far end, sees only that the wallet collected money from you.
This is the part people get backwards. A wallet does not hide a gambling payment from your bank in any meaningful sense, because the collection from your funding source still appears on your statement under the wallet's name. What it hides is the direction of travel, which is thin cover and should not be the reason you choose the rail.
What it genuinely hides is the instrument. The site never holds your card number, so there is nothing for it to store, reuse or lose. Compared with handing a long card number to a cashier you have known for five minutes, that is a real and specific improvement, and it is the honest case for the family.
Party
What it can see
What it gets to decide
You
A single confirmation screen
Whether to confirm at all
The cash desk
A wallet identifier and the amount
Whether the rail is offered and what the floor is
The wallet
Both the merchant and your funding source
Whether it will process for gambling at all
Your bank or issuer
A collection by the wallet
Whether the wallet's own request is allowed
What each party knows during one wallet deposit
The desk never reaches your account directly. It asks the wallet, and the wallet decides what to reach for.
The wallet decides whether gambling happens at all
A consumer wallet is not a neutral pipe. It runs an acceptable use policy, and gambling is one of the categories that policy singles out. In practice this means a merchant is not simply free to accept wallet payments because it has a payments page; it has to be a merchant the wallet has agreed to process gambling for, in a country where the wallet is willing to do that.
Which is why this rail has a strange on-or-off quality. Either the button is present in the cashier and the payments go through smoothly, or the rail is absent and no amount of fiddling produces it. There is very little middle ground, and when a site that used to show the button stops showing it, the change almost always happened on the wallet's side rather than the site's.
The useful consequence is that the presence of the button is itself a signal. A wallet that vets its gambling merchants has done a thin piece of due diligence on your behalf. Thin is the operative word: it is not a substitute for checking the operator's licence yourself, which is the only check that tells you who hears a complaint.
What is behind the wallet matters more than the wallet
A wallet can hold a balance, and it can hold links to a debit card and to a bank account. Those three funding sources behave differently and the difference shows up at the worst moment. A balance pays instantly and asks nobody. A linked debit card triggers a card pull in the background, with everything that implies, including whatever controls your issuer applies to gambling merchants. A linked bank account is slower and quieter.
The wallet chooses between them according to rules you can partly set and partly not. If a balance is sitting there, it generally goes first. If it is short, the shortfall is collected from the next source in line, which means one deposit can produce two entries at your bank for reasons that look arbitrary from the outside.
So when a wallet deposit fails and the wallet itself is fine, suspect the funding source. The behaviour you are seeing is a card refusal wearing a wallet's clothes, and the place to look is the same place you would look for a plain debit card refusal.
Credit behind the wallet does not get around the ban
Britain removed credit as a funding source for gambling, and the rule was deliberately written to follow the money rather than the plastic. A deposit funded from a credit card through an intermediary is still a deposit funded from credit, and the wallets operating here apply that on their own side rather than waiting to be told.
In day-to-day terms, this is why a wallet that happily uses your credit card for a train ticket will refuse to use it for a cash desk, and will usually say so plainly. The refusal is not a glitch and reconnecting the card will not change it. You either have a debit source attached or the rail is closed to you.
There is a second-order effect worth knowing. Because the wallet has to establish what kind of card it is holding, a newly added card can be refused while that is still settling, which looks identical to a ban refusal. If you need the reasoning behind the rule itself rather than its symptoms, it is on the page about the credit card ban.
The deposit path, step by step
The sequence is short but it has more handovers than a card payment. You pick the rail in the cashier and enter an amount. The cashier hands you to the wallet, usually in a new window, and the wallet asks you to confirm you are you. You confirm the payment inside the wallet, not inside the cashier. The wallet answers the cashier, and the cashier credits your balance.
Two of those handovers are fragile. The window can be closed by a pop-up blocker or by the phone switching apps, in which case the wallet may have taken the money while the cashier never heard the answer. And the final return to the cashier is what actually posts the credit, so a session that dies on the way back leaves the payment in a state neither party will describe confidently.
That is the usual cause of a deposit that has left your wallet and is not on your balance. Do not repeat it. One attempt in an unknown state is a reconciliation job; two attempts is two holds and a reason for the desk to pause the account while it works out what happened, which is covered under a deposit that has not arrived.
Why a payout back into the wallet usually works
This is the strongest argument for the rail and it is a structural one. A wallet is an account, it has an owner, and it can receive money as easily as it can send it. That satisfies the one thing a licensed operator has to be able to show, which is that the money went back to the person it came from, by the route it came by.
So where the wallet was accepted on the way in, it is nearly always available on the way out, and the leg from the cash desk to the wallet tends to be the quick part of the journey. The slow part is upstream of it: the review the site does before releasing anything, which is the same review regardless of rail and is described under how a payout is processed.
What the rail does not do is compress the review. A wallet payout that arrives in minutes once released was still waiting hours or days to be released, and the figures that matter are in the site's own terms rather than in the rail's reputation. The general shape of that wait is set out under how long a payout takes.
The linked card is a separate story
Here is where expectations most often break. A payout comes back into the wallet. It does not continue automatically onto the debit card or the bank account you funded the wallet from. The journey has two legs and the operator is only responsible for the first one.
Moving money out of the wallet and into your bank is a second transaction that you initiate, on the wallet's timetable rather than the site's, and it is governed entirely by the wallet's rules about withdrawals to a bank. If your mental model was card in, card out, the second leg appears out of nowhere and feels like a delay someone caused.
Treat the wallet, then, as a destination rather than a transit point. If what you actually want is money in your current account with no second step, a rail that terminates at the bank is the better choice, and the open banking route is the one built for exactly that.
Three failures that look the same and are not
Wallet refusals are famously uninformative because the party that refused is not the party showing you the screen. There are really only three cases, and separating them takes one look in each of two places.
Case one: the rail is not offered for your account at all, so the button is missing or greyed. That is the wallet's merchant policy or the site's regional configuration, and nothing you do at the payment screen touches it. Case two: the button works, the wallet opens, and the wallet declines. Open the wallet's own activity list; the refusal is recorded there with a reason, and that reason is the only honest account of what happened. Case three: the wallet approved and the funding source refused. The wallet will show an approval and a failed collection, and the fix is at your bank.
The one move that makes all three worse is retrying. Each attempt can leave a hold, and a pattern of attempts reads to a compliance system exactly like someone testing instruments. Authorised, taken and reversed look nearly identical on a statement, and a second attempt made before you know which one you are looking at creates a second problem rather than solving the first.
Currency, conversion and whose rate you get
If your wallet holds pounds and the cash desk charges in pounds, nothing here applies. If either side differs, somebody converts, and the party that converts sets the rate and the margin. The margin is where a quiet amount of money goes, and it is charged on the way in and again on the way out.
The wallet will usually offer to do the conversion itself, and that offer is the default rather than the cheapest option. The alternative is to let the funding source convert, which the wallet presents as a choice buried behind a link. Neither rate can be quoted in advance by anyone except the party quoting it, so the only reliable figure is the one on the confirmation screen before you press the button.
The structural fix is to not convert twice. Hold the wallet in the currency the cash desk charges in, or pick a cash desk that charges in your currency. A multi-currency account makes this manageable and introduces its own traps, which are covered on the page about app-based accounts.
What the wallet does not protect you from
Consumer wallets are known for stepping in when a purchase goes wrong. That protection is built for goods and services, where there is something that either arrived or did not, and gambling is outside it. A deposit that was credited and then lost at a game is not a failed delivery, and no dispute process treats it as one.
What the wallet can help with is narrower and still worth knowing: a payment taken twice, a payment taken and never credited, a collection from a source you did not authorise. Those are payment faults, they are recorded on both sides, and the wallet has a mechanism for them.
For everything that is a dispute with the operator rather than with the rail, the route runs through the site's own complaints process and then to the body named in its terms. That is a different machine with different evidence requirements, and the wallet has no standing in it at all.
Two sets of checks, and the name that has to match
Using a wallet means being verified twice, by two organisations, to different standards. The wallet verified you when you opened it. The cash desk verifies you separately, and it cannot accept the wallet's work as a substitute, because its licence obliges it to do its own.
The name is where this bites. The wallet's registered name, the name on the cash desk account and the name on the document you upload all have to be the same person. A wallet opened years ago under a previous surname, or a business wallet, or a wallet registered at an old address, all pass for shopping and then fail at the exit of a cash desk. Fixing a name on a wallet is slow, and it is slowest when a balance is waiting behind it.
Do the mismatch check before the first deposit, not after a win. What the documents are for and the order they are usually asked in is on the page about identity checks.
When another rail is the better pick
The wallet is the right answer when you want distance between a cash desk and your card, and when you are content for the money to come back into the wallet and sit there. It is the wrong answer when you want the shortest possible path to your current account, when the rail is simply not offered, or when your funding source is going to refuse anyway.
It is also the wrong answer if you have a gambling control set at your bank and you are reaching for a wallet because it goes around it. The block exists because you decided it should; routing round it is a decision made by a worse version of you, and the page about bank gambling blocks is the one to read instead. Device wallets are worth a mention here too, since they are often grouped with this family and are not really in it. Paying by phone with a stored card and the equivalent on Android both present a substitute number for a card, so the rail underneath is a card pull and the card's rules govern.
Item
Figure
Keeping your card number away from the site
Its real strength
Getting a payout released any sooner
No effect at all
Reaching your current account in one step
Two legs, second one is yours
Being available wherever you want it
The wallet vets the merchant
What the wallet rail is strong and weak at, as a shape rather than a score Ordinal comparison only: the bars rank these against each other and are not measurements of anything.
Questions people ask
Why can I not see PayPal in a cashier that used to offer it?
Availability on this rail is set by the wallet rather than the site, and it is set per merchant and per country. When the button disappears it is usually because that agreement changed, which is why support can rarely do more than confirm the rail is off. Nothing on your side causes it and nothing on your side restores it.
Does a wallet deposit show on my bank statement?
Yes, but as a collection by the wallet rather than as the cash desk. The merchant name is hidden; the fact that money left your account is not. If the deposit came from a balance already sitting in the wallet, there is no new bank entry at all, because nothing was collected at that moment.
Can I withdraw to a wallet I did not deposit from?
Normally no. The operator pays back along the route the money arrived on so that it can show the funds returned to the same person, and a different wallet breaks that proof. If the original route genuinely cannot receive a payout, a replacement has to be registered and verified in your own name first.
The wallet says the payment went through but my balance is empty.
The answer from the wallet did not reach the cashier, most often because the window closed on the way back. The money exists and is recoverable on one side or the other, so the job is reconciliation rather than payment. Send the wallet's transaction reference, the exact amount and the time with its zone to support, and do not pay again while you wait.
Is buyer protection any use for a casino deposit?
No. That protection covers goods and services that did not turn up or did not match, and a credited gambling balance is neither. The wallet will still look at a genuine payment fault, such as a double charge or a collection you never approved, because those are errors on the rail itself.
Will a bonus be available if I deposit this way?
That depends on the site, and some promotions exclude particular rails outright. The exclusion is always written into the offer terms rather than shown on the payment screen, so it is worth reading the terms before choosing the method. The size and conditions of any offer are set by the operator and change without notice.
Can I keep a card on the wallet purely for cash desks?
You can attach several sources and nominate which one is preferred, although the wallet still has the last word when a balance is involved. Keeping gambling on one source does make statements easier to read and limits easier to hold. It does not create any extra protection, since the source itself is the thing being charged.
Do I pay tax on money that arrives in my wallet from a cash desk?
A player in the United Kingdom pays no tax on gambling winnings, and the rail the money travelled by does not alter that. The wallet entry is a record, not a taxable event. The duty in this market sits with the operator rather than with you.
What if I am on the self-exclusion register and the wallet still works?
The register closes the door at the operator, not at the wallet, so a working wallet is not a sign that anything has lapsed. Any licensed site you reach will refuse the account rather than the payment. Looking for a site that will accept it means leaving British licensing altogether, and with it the rules and the place to complain; the National Gambling Helpline is on 0808 8020 133.
Is there a fee for moving the money from the wallet to my bank?
That is set entirely by the wallet and varies by speed and by account type, so the only figure to trust is the one shown in your own wallet at the moment you make the transfer. Since this second leg is yours rather than the operator's, no payment terms at the cash desk cover it.
 UK Cash DeskOpen the cashier


 100% up to £100 on your first deposit